Somewhere between “good enough” and “as high as possible,” most people lose track of what a CIBIL score actually buys them. Is going from 700 to 750 worth chasing? Does 800 get you meaningfully more than 750? The honest answer, backed by real lender data, is that these jumps are not equally valuable, one genuinely changes what you pay, the other mostly just confirms what you already had.
Here is what each score band actually means in practice, with real numbers showing exactly where the difference matters and where it quietly stops mattering.
The Score Bands in Context
| Score Range | Category | What Lenders Generally See |
|---|---|---|
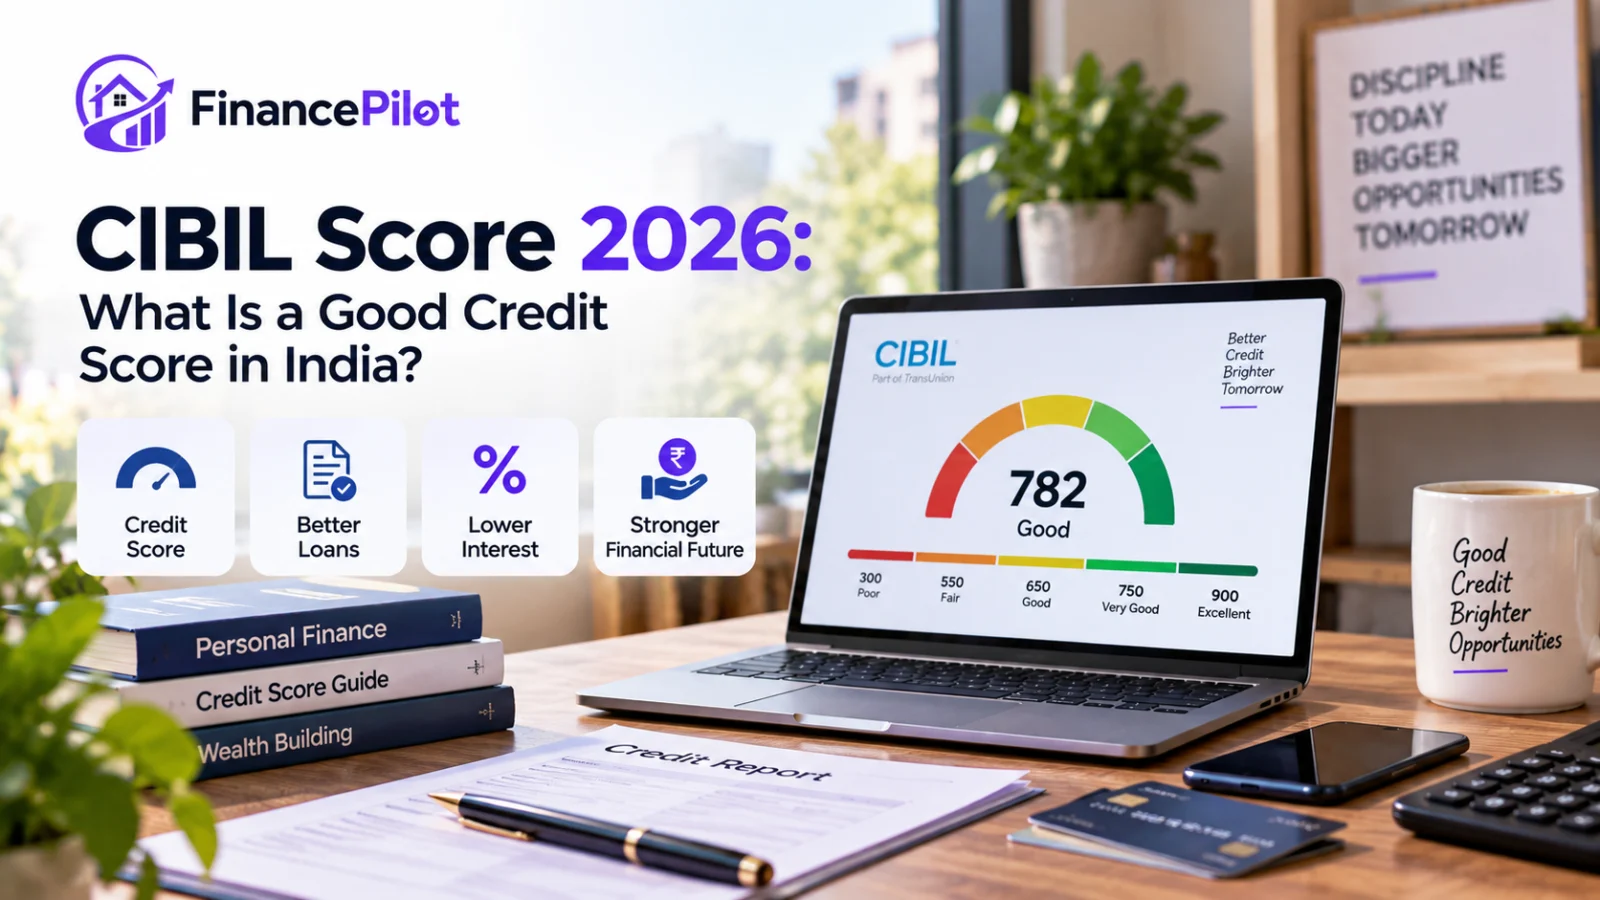
| 650 to 699 | Fair | Approval possible, but at higher rates and lower amounts |
| 700 to 749 | Good | Approval improves, still not the best pricing |
| 750 to 799 | Very Good | Treated as low risk, competitive rates open up |
| 800 to 900 | Excellent | Best available rates, though gains over 750 are marginal |
A Real Worked Example: The Rate Gap in Rupees
Consider a ₹5 lakh personal loan over a 5 year tenure, priced according to the rate tier each score typically unlocks. At a 700 score, a realistic quoted rate might sit around 14 percent annually, producing an EMI of roughly ₹11,630 and total interest of approximately ₹1,98,000 over the tenure. At a 750 score, the same loan at a more competitive 11.5 percent works out to an EMI of about ₹10,995, with total interest closer to ₹1,59,700. At an 800 score, a further improved rate of around 10.5 percent brings the EMI down to roughly ₹10,745, with total interest near ₹1,44,760.
Laid out plainly, moving from 700 to 750 saves approximately ₹38,300 in total interest on this loan. Moving from 750 to 800 saves only around ₹14,900, less than half the earlier gain, on an identical loan amount and tenure. This is the pattern worth internalising, the value of a higher score is not linear, it front-loads heavily in the 700 to 750 range and tapers off considerably beyond it.
Loan Amount Eligibility Also Widens, Then Plateaus
Beyond interest rate, your score also shapes how much a lender is willing to extend in the first place. A borrower at a 780 score might be approved for a ₹10 lakh personal loan, while an otherwise similar applicant at 640 may only qualify for ₹3 to 5 lakh, since lenders read a lower score as a signal to cap exposure more conservatively. Between 750 and 800, however, this eligibility ceiling tends to widen only modestly further, since most lenders have already extended their most generous terms by the time a borrower clears the 750 threshold.
Approval Speed and Documentation Scrutiny
A 700 score generally still requires the standard documentation and underwriting review most lenders apply to every applicant. At 750 and above, several digital lenders and NBFCs offer meaningfully faster, sometimes near-instant, pre-approval decisions, since the score itself substitutes for some of the manual scrutiny a borderline application would otherwise receive. This gap between 750 and 800 narrows considerably, since both scores generally clear the same fast-track thresholds at most lenders.
Why Returns Diminish So Sharply Above 750
The reason this pattern holds is straightforward once you understand how lenders actually price risk. Most lenders group scores into a small number of pricing tiers rather than adjusting the rate for every single point of difference. A 750 score and an 800 score frequently land in the same top pricing tier at a given lender, meaning both get quoted an identical rate despite the 50 point gap between them. In practical terms, a score of 800 and a score of 850 will typically receive the same interest rate offers from most lenders in 2026, and the difference between a 760 and an 820 score is rarely significant in rupee terms on a standard personal loan.
What Actually Separates 700 from 750
This is the gap genuinely worth closing if you sit in it. A 700 score often sits close to the boundary that stricter lenders use as their internal cutoff, meaning some banks may decline the application outright or push it toward a higher-priced NBFC alternative, while an identical applicant at 750 clears that same lender’s standard, better-priced tier without additional scrutiny. Our guide to why personal loan applications get rejected covers how a borderline score like 700 interacts with other factors, such as your FOIR, to tip an application toward approval or decline.
What Actually Separates 750 from 800
Very little, in most practical lending scenarios. Once you clear 750, the meaningful battle has generally already been won, most major lenders have already placed you in their best pricing tier and highest eligibility band. Chasing 800 specifically, once you are comfortably above 750, delivers diminishing financial returns relative to the effort required, since you are optimising a factor that has already stopped moving the number that matters most, your actual interest rate and loan amount.
Should You Actively Try to Push Your Score Past 750
If you are currently below 750, yes, the effort is genuinely worthwhile given the rupee difference demonstrated above. If you are already comfortably past 750, the more useful focus shifts from maximising your score further to simply maintaining it, continuing to pay on time, keeping your credit utilisation below 30 percent, and avoiding multiple loan applications in a short window. These habits protect the pricing tier you have already earned without requiring any additional active effort to chase a marginal, largely symbolic improvement. Our guide to improving your CIBIL score fast covers these same habits in more depth if your current score still sits below the 750 threshold where the real financial gains are concentrated, and our broader guide to what counts as a good CIBIL score in 2026 covers how these bands are calculated in the first place.
Frequently Asked Questions
Is a 750 CIBIL score significantly better than 700 for a personal loan?
Yes, meaningfully. On a ₹5 lakh, 5 year personal loan, moving from a 700 to a 750 score can save approximately ₹38,000 in total interest, since 700 often sits near the cutoff some stricter lenders use, while 750 clears most lenders’ standard, better-priced tier.
Is an 800 CIBIL score much better than 750?
Not by much in practical terms. Most lenders group scores above 750 into similar top pricing tiers, so an 800 score typically receives interest rates and loan eligibility very close to what a 750 score already unlocks, with the rupee savings from this gap being considerably smaller than the gap between 700 and 750.
What CIBIL score do I need for the lowest interest rate?
Generally, 750 or above is sufficient to access most lenders’ best pricing tier. Pushing further toward 800 or higher rarely reduces your rate further, since lenders typically do not offer meaningfully better pricing purely for scores above this threshold.
Does a higher CIBIL score always mean a higher loan amount?
Generally yes, up to a point. Loan amount eligibility widens noticeably as your score improves from the 600s toward 750, but this ceiling tends to widen only modestly further between 750 and 800, since most lenders have already extended their most generous terms by the 750 mark.
Should I keep trying to improve my CIBIL score once it crosses 750?
Maintaining your score matters more than actively maximising it once you are past 750. Continuing to pay on time and keeping utilisation low protects the favourable pricing tier you have already earned, while chasing an even higher score delivers only marginal additional financial benefit.