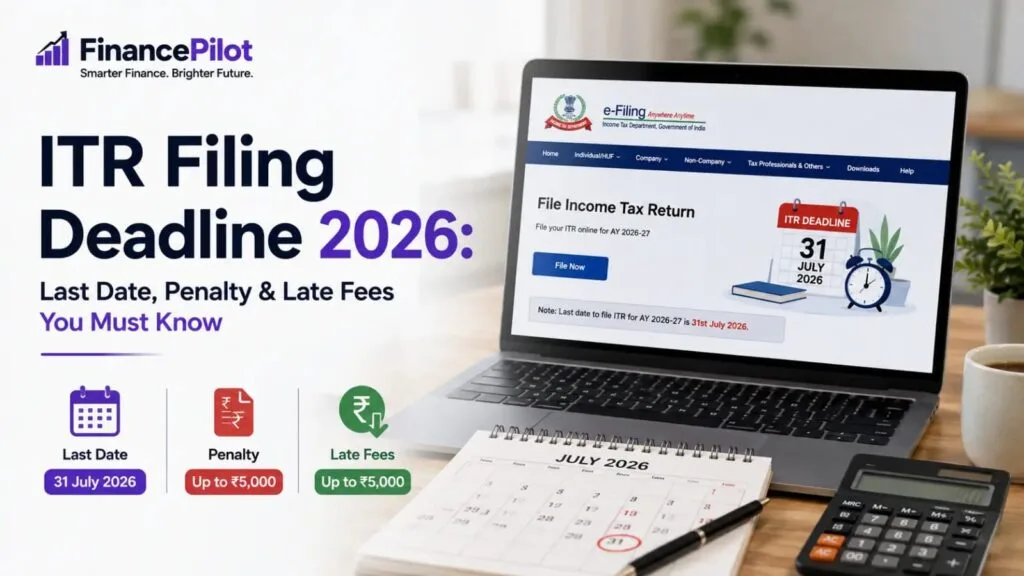
If you are reading this after checking today’s date, here is the important part upfront. For most taxpayers, the ITR filing window for FY 2025-26 (AY 2026-27) has already closed. Salaried individuals filing ITR-1 or ITR-2 had until July 31, 2026, and non-audit business or professional taxpayers filing ITR-3 or ITR-4 had until August 31, 2026. If either of these applied to you and you have not filed yet, you are not out of options, but every day now adds to what you owe.
This guide covers exactly where things stand, what penalties apply if you missed your deadline, and how to file a belated return correctly before the final December 31, 2026 cutoff.
ITR Deadlines for AY 2026-27 at a Glance
| Taxpayer Category | ITR Form | Due Date | Status Today |
|---|---|---|---|
| Salaried individuals, no audit | ITR-1, ITR-2 | 31 July 2026 | Passed |
| Business or professional, no audit | ITR-3, ITR-4 | 31 August 2026 | Passed |
| Taxpayers requiring tax audit | ITR-3, ITR-5, ITR-6 | 31 October 2026 | Upcoming |
| Belated return for all above categories | Any applicable form | 31 December 2026 | Open now |
Budget 2026 extended the non-audit deadline for ITR-3 and ITR-4 filers to August 31, a permanent one-month cushion compared to earlier years, largely to give professionals, freelancers and small business owners extra time. If your business requires a tax audit, you still have until October 31, 2026, so this deadline pressure does not apply to you yet.
If You Missed Your Deadline: The Belated Return Option
Missing your original due date does not mean you have lost the ability to file. Under Section 139(4) of the Income Tax Act, you can still file what is called a belated return any time up to December 31, 2026, for AY 2026-27. This is the same ITR form you would have filed originally, just submitted after the due date, and it comes with a financial cost attached.
Late Filing Fee Under Section 234F
The fee for filing after your due date is fixed by income level and does not scale further with how many additional days you delay, as long as you file before December 31.
| Total Income | Late Filing Fee |
|---|---|
| Up to ₹2.5 lakh (below basic exemption) | Nil |
| Above ₹2.5 lakh, up to ₹5 lakh | ₹1,000 |
| Above ₹5 lakh | ₹5,000 |
This fee is mandatory and cannot be waived once you file after the due date, regardless of your reason for the delay. It is worth noting that total income here refers to your gross total income before applying the Section 87A rebate, so even if your final tax liability works out to zero after rebate, the Section 234F fee can still apply if your gross income crosses the relevant threshold.
Interest Under Section 234A
Beyond the flat late fee, if you have any unpaid tax outstanding, Section 234A charges interest at 1 percent per month, or part of a month, on that unpaid amount, calculated from the day after your original due date until the date you actually file. This is simple interest, and it keeps accumulating for every partial month you delay, so a return filed on the last day of a month costs the same interest as one filed on the first day of that same month.
What You Lose by Filing Late
Beyond the direct financial cost, a belated return carries a few consequences that are easy to overlook. Most business losses and capital losses, including losses from selling stocks, mutual funds or property, cannot be carried forward to future years if your return is filed after the original due date. This is one of the most financially significant costs of late filing for investors, since a capital loss that could have offset future gains is permanently lost rather than merely delayed. Our capital gains tax guide explains how capital losses are normally set off and carried forward when filed on time, and the capital gains calculator can help you work out what a lost carry-forward might actually cost you over future years. House property loss is a notable exception and can still be carried forward even with a belated return, subject to standard conditions.
How to File a Belated Return Now
Filing a belated return follows the same process as a regular return on the income tax e-filing portal, with one added step, paying your late fee and any applicable interest through Challan 280 under self-assessment tax before you submit. Log in with your PAN, select AY 2026-27, choose the correct ITR form based on your income sources, and the portal will prompt you to pay the applicable Section 234F fee as part of the self-assessment tax calculation before you can proceed to submission.
What Happens If You Miss December 31 Too
If you do not file even a belated return by December 31, 2026, your only remaining route is an updated return, or ITR-U, under Section 139(8A). This allows you to file after the belated return window closes, but it comes at a meaningfully higher cost, an additional tax ranging from 25 to 50 percent on top of your regular tax and interest, depending on how late the updated return is filed. This route exists mainly as a compliance safety net for genuine omissions, not as a substitute for timely filing, and it should generally be treated as a last resort.
Revised Returns Now Have More Room
If you already filed on time but later spot an error, Budget 2026 extended the revised return window from the earlier December 31 cutoff to March 31, 2027, giving taxpayers a meaningfully longer runway to correct genuine mistakes such as a missed deduction or an incorrect income figure, without the late filing consequences that apply to belated returns.
Frequently Asked Questions
Has the ITR deadline for AY 2026-27 been extended?
As of now, the original deadlines of July 31, 2026 for ITR-1 and ITR-2 and August 31, 2026 for non-audit ITR-3 and ITR-4 have not been extended. Any future extension would be announced officially by the CBDT, and taxpayers should not assume one will happen.
What is the last date to file a belated ITR for AY 2026-27?
You can file a belated return under Section 139(4) any time up to December 31, 2026. After this date, filing is only possible through an updated return, or ITR-U, which carries a significantly higher additional tax cost.
How much is the penalty for late ITR filing in 2026?
Under Section 234F, the late filing fee is ₹5,000 if your total income exceeds ₹5 lakh, and ₹1,000 if your income is ₹5 lakh or below. No fee applies if your total income is below the basic exemption limit of ₹2.5 lakh.
Can I still carry forward my capital losses if I file a belated return?
No. Most business and capital losses cannot be carried forward to future years if your return is filed after the original due date. House property loss is an exception and can still be carried forward even in a belated return.
What is the difference between a belated return and an updated return?
A belated return is filed under Section 139(4) any time before December 31, 2026, with a fixed late fee under Section 234F. An updated return, or ITR-U, is filed after that window closes and carries an additional tax of 25 to 50 percent on top of your regular tax liability, making it a considerably costlier option.