If you have taken a home loan for an under-construction flat, you may have noticed something odd on your first repayment statement, a monthly charge that is smaller than the EMI your loan calculator promised, and one that never seems to reduce your outstanding loan balance no matter how many months you pay it. This is Pre-EMI, and understanding exactly how it works can save you from an unpleasant surprise when your real EMI finally kicks in.
This guide explains what Pre-EMI actually is, the exact formula banks use to calculate it, how it compares to paying full EMI from day one, and the specific tax rules that apply to it.
What Pre-EMI Actually Means
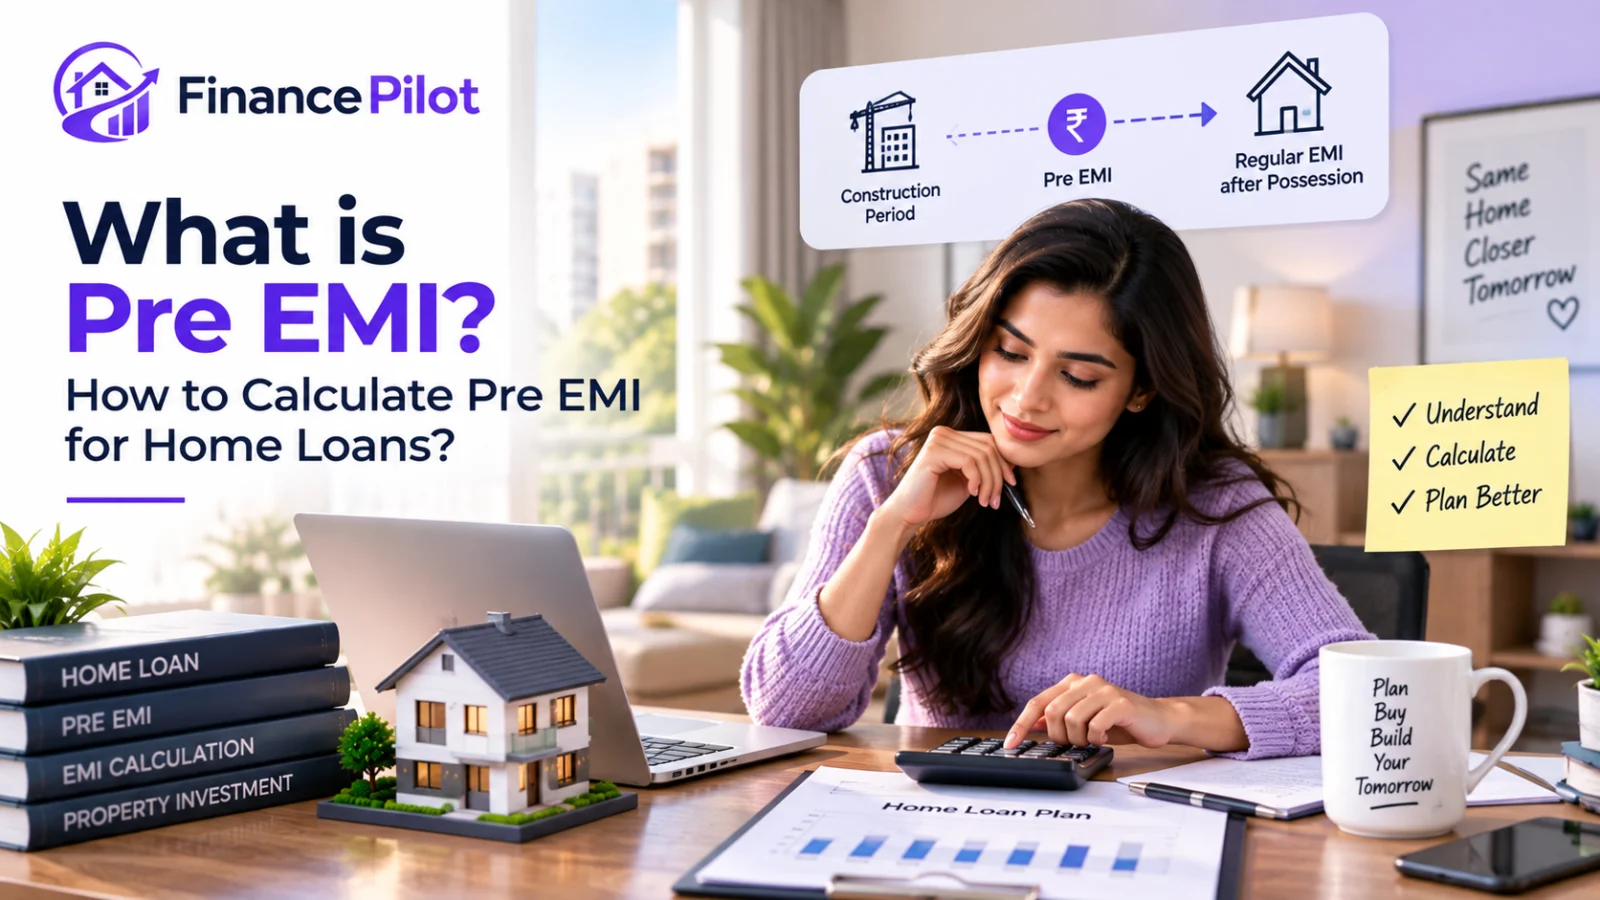
When you take a home loan for a property still under construction, the bank does not hand over the entire sanctioned amount at once. Instead, funds are released in stages, tied to the builder’s construction progress, commonly across four to ten disbursements spread over 18 to 36 months depending on the project’s size. During this period, rather than paying no EMI at all, most banks require you to pay Pre-EMI, an interest-only payment calculated purely on the amount actually disbursed so far, not on the full sanctioned loan amount.
Crucially, Pre-EMI does not touch your principal at all. Every rupee you pay during this phase covers interest only, which means your outstanding loan balance stays exactly where it started until full disbursement happens and your regular EMI schedule begins.
The Pre-EMI Formula
The calculation itself is simple:
Pre-EMI = Disbursed Loan Amount × (Annual Interest Rate ÷ 12)
Since only the disbursed portion is used in this calculation, your Pre-EMI amount rises in steps every time the bank releases a fresh tranche of funds to the builder, rather than staying fixed like a regular EMI would.
A Worked Example
Consider a ₹50 lakh home loan at 8.5 percent annual interest for a project expected to take two years to complete. In month one, the bank disburses ₹5 lakh to the builder for the foundation stage. Your Pre-EMI for that month works out to ₹5,00,000 multiplied by 8.5 percent divided by 12, which comes to approximately ₹3,542. After six months, once the structure stage is complete, the bank releases another ₹10 lakh, bringing total disbursement to ₹15 lakh. Your Pre-EMI now rises to roughly ₹10,625 per month. This step-up continues at every disbursement milestone until the property is fully funded and ready for possession, at which point your Pre-EMI phase ends and your regular, principal-plus-interest EMI begins.
How Disbursement Stages Typically Work
Disbursement schedules are not standardised across the industry, some banks release funds in as few as four stages, tied to milestones like foundation, plinth, structure and finishing, while others use eight to ten more granular stages. Delays in construction directly extend your Pre-EMI phase, since disbursement is linked to actual progress, not a fixed calendar. It is worth getting the exact disbursement schedule in writing from your bank before signing, since this directly determines how long you will be paying Pre-EMI and how quickly it steps up.
Pre-EMI vs Full EMI During Construction
Most banks that offer construction-linked home loans give you a choice between Pre-EMI and paying full EMI from the very first disbursement.
| Feature | Pre-EMI | Full EMI During Construction |
|---|---|---|
| Monthly payment during construction | Lower (interest only on disbursed amount) | Higher (principal plus interest on disbursed amount) |
| Principal reduction during construction | None | Begins immediately |
| Total interest over loan lifetime | Higher | Lower |
| Loan tenure impact | Full tenure starts after possession | Effectively shortens overall repayment period |
| Best suited for | Buyers also paying rent during construction | Buyers with spare cash flow who want to minimise total interest |
Choosing full EMI during construction typically costs more per month upfront, since you are already covering a portion of the principal alongside interest, but it reduces your total interest paid over the life of the loan since your outstanding balance starts shrinking earlier. Choosing Pre-EMI keeps the near-term outgo lower, which matters if you are simultaneously paying rent on your current home while your new one is being built, but it comes at the cost of a higher total interest bill over time.
How Pre-EMI Interest Is Taxed
This is a detail many first-time buyers overlook. Interest paid during the Pre-EMI phase is not deductible in the year you actually pay it. Instead, under Section 24(b) of the Income Tax Act, the total pre-construction interest accumulated is aggregated and becomes deductible in five equal instalments, starting from the financial year in which construction is completed and possession is handed over. For example, if your total Pre-EMI interest across the construction period came to ₹2 lakh, you would be able to claim ₹40,000 as a deduction in each of the five years following possession, in addition to the regular interest deduction on your post-possession EMI for that same year. This combined deduction, for self-occupied property, remains subject to the overall ₹2 lakh annual cap on home loan interest deduction under the old tax regime, a limit that is not available at all under the new regime. Our guide to the RBI repo rate covers how your loan’s interest rate itself is likely to move over the construction period, which directly affects how much Pre-EMI interest actually accumulates.
Why Pre-EMI Can Quietly Cost More Than Expected
The reason Pre-EMI increases your total interest burden is straightforward but easy to underestimate. Since your principal remains untouched throughout the entire construction period, potentially two to three years for a large project, you are effectively paying pure interest for an extended stretch before your loan even starts amortising. If construction runs behind schedule, which remains common across many Indian real estate markets, your Pre-EMI phase extends correspondingly, adding further to the total interest cost without shortening your eventual repayment tenure.
When Pre-EMI Makes Sense
Pre-EMI genuinely suits buyers who need the lowest possible monthly outgo during construction, particularly those simultaneously paying rent for their current accommodation, since covering both a full EMI and rent at the same time can strain monthly cash flow considerably. It can also make sense if you expect a meaningful income increase by the time possession happens, allowing you to comfortably absorb the jump to full EMI later without having overpaid unnecessarily during a period when you had less financial flexibility.
What to Check With Your Bank Before Choosing
Before committing to either option, get the exact disbursement schedule in writing, confirm whether your specific loan allows switching between Pre-EMI and full EMI during construction, and ask explicitly how the bank handles a construction delay beyond the originally stated timeline, since some lenders cap the total Pre-EMI period regardless of project delays while others do not. If you are weighing this loan structure against other financing routes, our guide to loan against property covers an alternative for buyers who already own an asset they could leverage instead.
Frequently Asked Questions
What is the difference between Pre-EMI and full EMI?
Pre-EMI is an interest-only payment calculated on the loan amount disbursed so far during construction, with no reduction to your principal. Full EMI includes both principal and interest, and begins either from the first disbursement, if your bank allows that option, or automatically once the property is fully funded and possession is handed over.
How is Pre-EMI calculated?
Pre-EMI is calculated using the formula: Disbursed Loan Amount multiplied by the annual interest rate, divided by 12. Since it is based only on the amount actually disbursed, your Pre-EMI rises in steps as the bank releases further tranches of funds during construction.
Does Pre-EMI reduce my home loan principal?
No. Pre-EMI covers interest only on the disbursed amount, and your outstanding principal remains exactly the same throughout the entire Pre-EMI phase, regardless of how many months you pay it.
Is Pre-EMI interest tax deductible?
Not in the year you pay it. Under Section 24(b), accumulated pre-construction interest becomes deductible in five equal instalments starting from the year construction is completed, subject to the overall ₹2 lakh annual cap on home loan interest deduction for self-occupied property under the old tax regime.
Is Pre-EMI or full EMI better for an under-construction property?
It depends on your cash flow. Pre-EMI keeps your near-term monthly payment lower, which helps if you are also paying rent during construction, but full EMI from the start reduces your total interest cost over the loan’s lifetime since your principal begins shrinking earlier.