Every bank’s home loan page advertises a rate that sounds unbeatable, and almost none of them apply to the average applicant. The “starting from” figure you see in an ad is reserved for borrowers with a near-perfect credit score, a government or PSU salary, and often a lower loan-to-value ratio, while most actual applicants get quoted something noticeably higher once underwriting is done. Knowing which bank is genuinely cheapest for your specific profile matters far more than chasing the lowest number in an advertisement.
This guide compares where major Indian banks actually stand on home loan rates in 2026, what decides the rate you personally get, and how to evaluate lenders beyond the headline number.
Why “Lowest Rate” Depends Entirely on Who Is Asking
Home loan pricing in India is not a single number per bank, it is a range, and where you land in that range depends on your credit score, income category, loan-to-value ratio, and sometimes your gender. Public sector banks tend to advertise the lowest absolute starting rates, but these are typically reserved for government or defence employees with a CIBIL score above 750. Private banks generally quote a narrower, slightly higher range, but often process faster and extend that competitive rate to a broader set of private-sector salaried applicants.
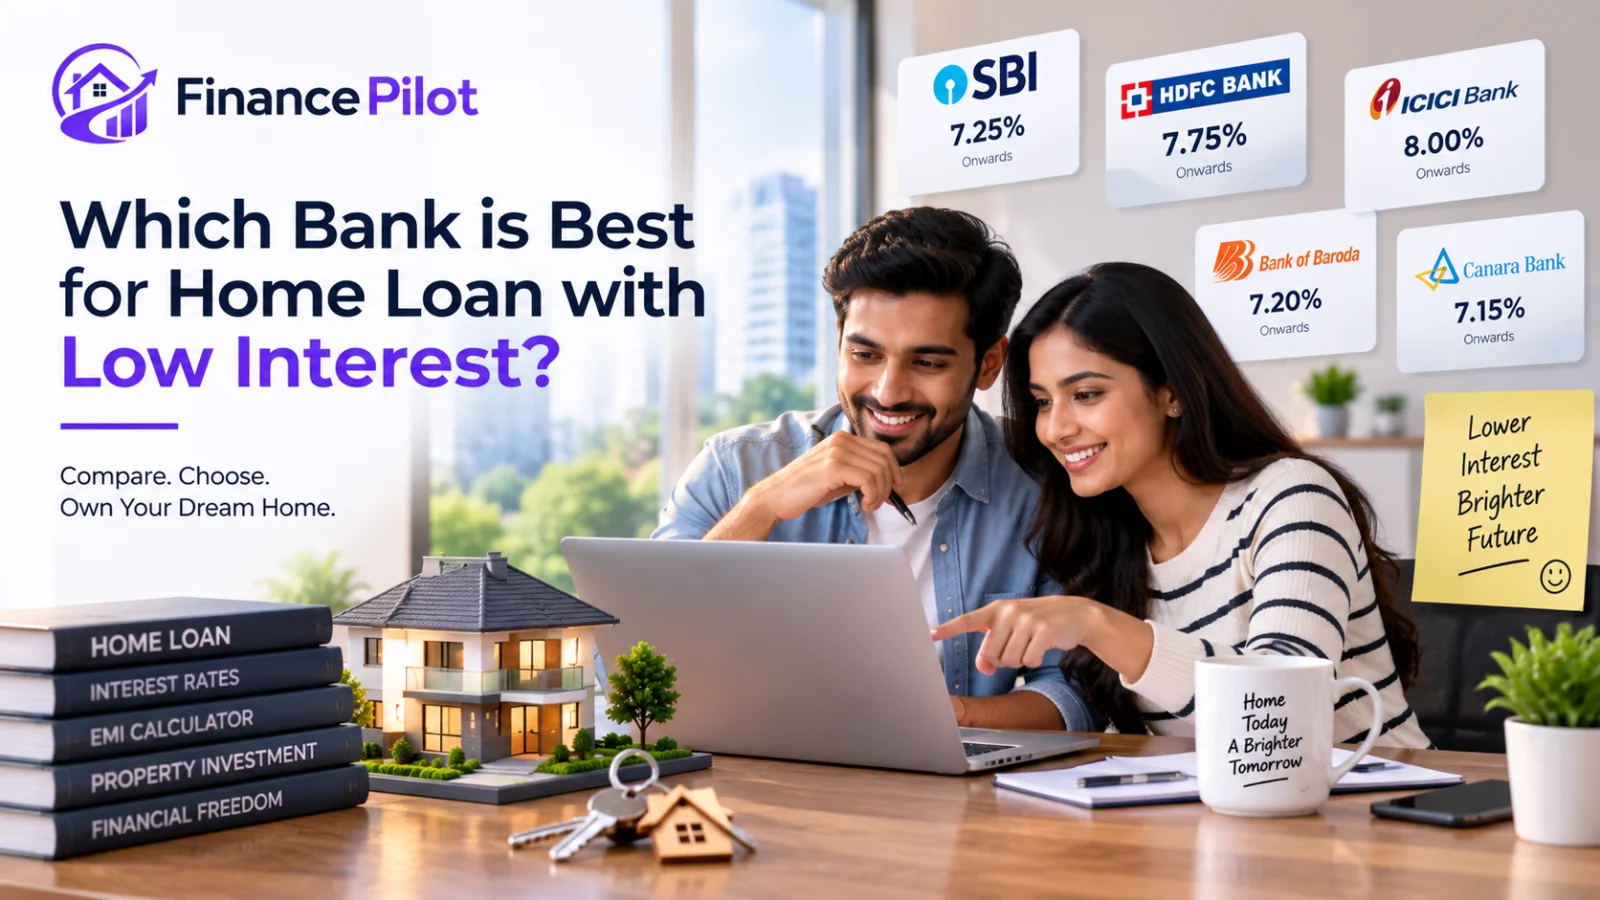
How Major Banks Compare in 2026
| Bank | Typical Starting Rate (p.a.) | Best Suited For |
|---|---|---|
| State Bank of India (SBI) | 7.25% to 8.70% | Government/PSU employees, high CIBIL scores |
| Punjab National Bank (PNB) | 7.45% to 8.55% | Government employees, salaried applicants |
| Bank of Baroda (BoB) | 7.45% to 8.40% | Government employees, women borrowers |
| Canara Bank | 7.50% to 8.55% | Government employees, salaried applicants |
| HDFC Bank | 7.75% to 8.75% | Private-sector salaried, premium properties |
| ICICI Bank | 7.75% to 8.75% | Private-sector salaried, faster digital processing |
| Axis Bank | 8.15% to 8.75% | Private-sector salaried, existing relationship customers |
| Bajaj Housing Finance | 7.25% onwards | Self-employed and non-traditional income profiles |
These figures are indicative ranges compiled from lender-published rates through 2026 and will vary by your specific credit profile, loan amount and the bank’s current offers, so treat this as a starting benchmark rather than a quote you can walk in and demand.
What Actually Decides Your Personal Rate
Your Credit Score
A CIBIL score of 750 or above generally unlocks a bank’s best-advertised slab across nearly every lender in this comparison. Scores between 700 and 750 typically see a modestly higher rate, while anything below 700 can mean a meaningfully higher rate or, in some cases, rejection outright, depending on the lender’s internal risk policy.
Government vs Private Sector Employment
Public sector banks consistently price their most competitive rates for government, defence and PSU employees, reflecting the lower perceived income risk in these categories. Private-sector salaried applicants generally see a somewhat higher starting point at the same banks, though the gap has narrowed as competition has intensified.
Loan-to-Value Ratio
A lower loan-to-value ratio, meaning a larger down payment relative to the property price, generally earns a better rate, since it reduces the lender’s exposure if the property needs to be repossessed and sold.
Women Co-Borrowers
Several public sector banks, including Bank of Baroda, extend a small additional rate concession, often around 0.05 percent, when a woman is a co-borrower or the primary applicant, a policy aimed at encouraging property ownership among women.
The RBI Repo Rate
Since most floating-rate home loans today are linked to the RBI’s repo rate through a Repo Linked Lending Rate structure, your rate moves in step with RBI policy decisions, typically within a quarter. Our guide to the RBI repo rate covers how the current steady rate environment is affecting EMIs and what a future rate change would mean for your specific loan.
Public Sector vs Private Banks: The Real Trade-Off
Public sector banks generally win on the headline rate, particularly for government employees and high-credit-score borrowers, but they can involve more documentation and a somewhat slower sanctioning process compared to private lenders. Private banks and housing finance companies like Bajaj Housing Finance tend to offer faster digital processing, more flexible eligibility for self-employed and non-traditional income applicants, and stronger customer service infrastructure, often at a small premium over the very lowest PSU rate. Whether that premium is worth paying depends on how much you value speed and flexibility versus shaving off a fraction of a percentage point in interest.
Why a 0.25 Percent Difference Actually Matters
It is tempting to dismiss small rate differences as negligible, but the math says otherwise over a long tenure. On a ₹50 lakh loan over 20 years, a 0.25 percent difference in interest rate translates to a difference of roughly ₹788 in monthly EMI, which compounds to close to ₹1.9 lakh in total interest paid over the full loan term. This is precisely why comparing actual quotes across two or three lenders, rather than accepting the first offer, is worth the extra effort for a loan of this size and duration.
Beyond the Interest Rate: What Else to Compare
The interest rate is the most visible number, but it is not the only cost that affects your total outgo. Processing fees typically range from 0.25 to 1 percent of the loan amount and vary meaningfully across lenders. Prepayment and foreclosure charges matter if you expect to repay early, since some lenders waive these on floating-rate loans while others do not. Loan tenure flexibility, often extending up to 30 years at several major banks, affects your monthly EMI directly, and the type of interest rate structure, whether MCLR-linked or repo-linked, determines how quickly a future RBI rate change actually reaches your EMI.
A Practical Way to Decide
Start by checking your CIBIL score, since this single number determines which slab of any bank’s rate range you actually qualify for. If you are a government or PSU employee with a strong credit score, a public sector bank is likely to offer the genuinely lowest rate available to you. If you are privately employed or self-employed, compare at least two or three private banks and housing finance companies directly, since their eligibility criteria and effective rates for your specific profile can differ meaningfully from what the headline advertised rate suggests. If you already own property and are considering leveraging it instead of taking a fresh purchase loan, our guide to loan against property covers how that route compares on rates and eligibility.
Frequently Asked Questions
Which bank currently offers the lowest home loan interest rate in India?
Public sector banks like SBI, PNB, Bank of Baroda and Canara Bank generally offer the lowest advertised starting rates in 2026, often in the 7.25 to 7.50 percent range, but this pricing is typically reserved for government or PSU employees with a CIBIL score above 750.
Do private banks ever offer better home loan rates than public sector banks?
For private-sector salaried applicants specifically, private banks like HDFC and ICICI can sometimes match or come close to public sector rates once relationship banking discounts or promotional offers are applied, even though their standard advertised starting rate is usually a touch higher.
How much does my credit score actually affect my home loan interest rate?
Significantly. A CIBIL score of 750 or above generally qualifies you for a lender’s best-advertised rate slab, while a score between 700 and 750 typically means a moderately higher rate, and scores below 700 can result in a meaningfully higher rate or rejection depending on the lender.
Is it worth switching lenders for a 0.25 percent lower home loan rate?
Often yes, for a large, long-tenure loan. On a ₹50 lakh loan over 20 years, a 0.25 percent rate reduction can save close to ₹1.9 lakh in total interest, though you should also factor in any balance transfer processing fees before deciding.
Do women get a lower home loan interest rate in India?
Several public sector banks, including Bank of Baroda, offer a small additional rate concession, typically around 0.05 percent, when a woman is the primary borrower or a co-borrower, though the exact concession and eligibility criteria vary by lender.